First Home Loan North Brisbane
Need an easy to manage first home loan?
From grants and contracts to paperwork, we'll help you understand exactly what you can borrow and what schemes you qualify for.
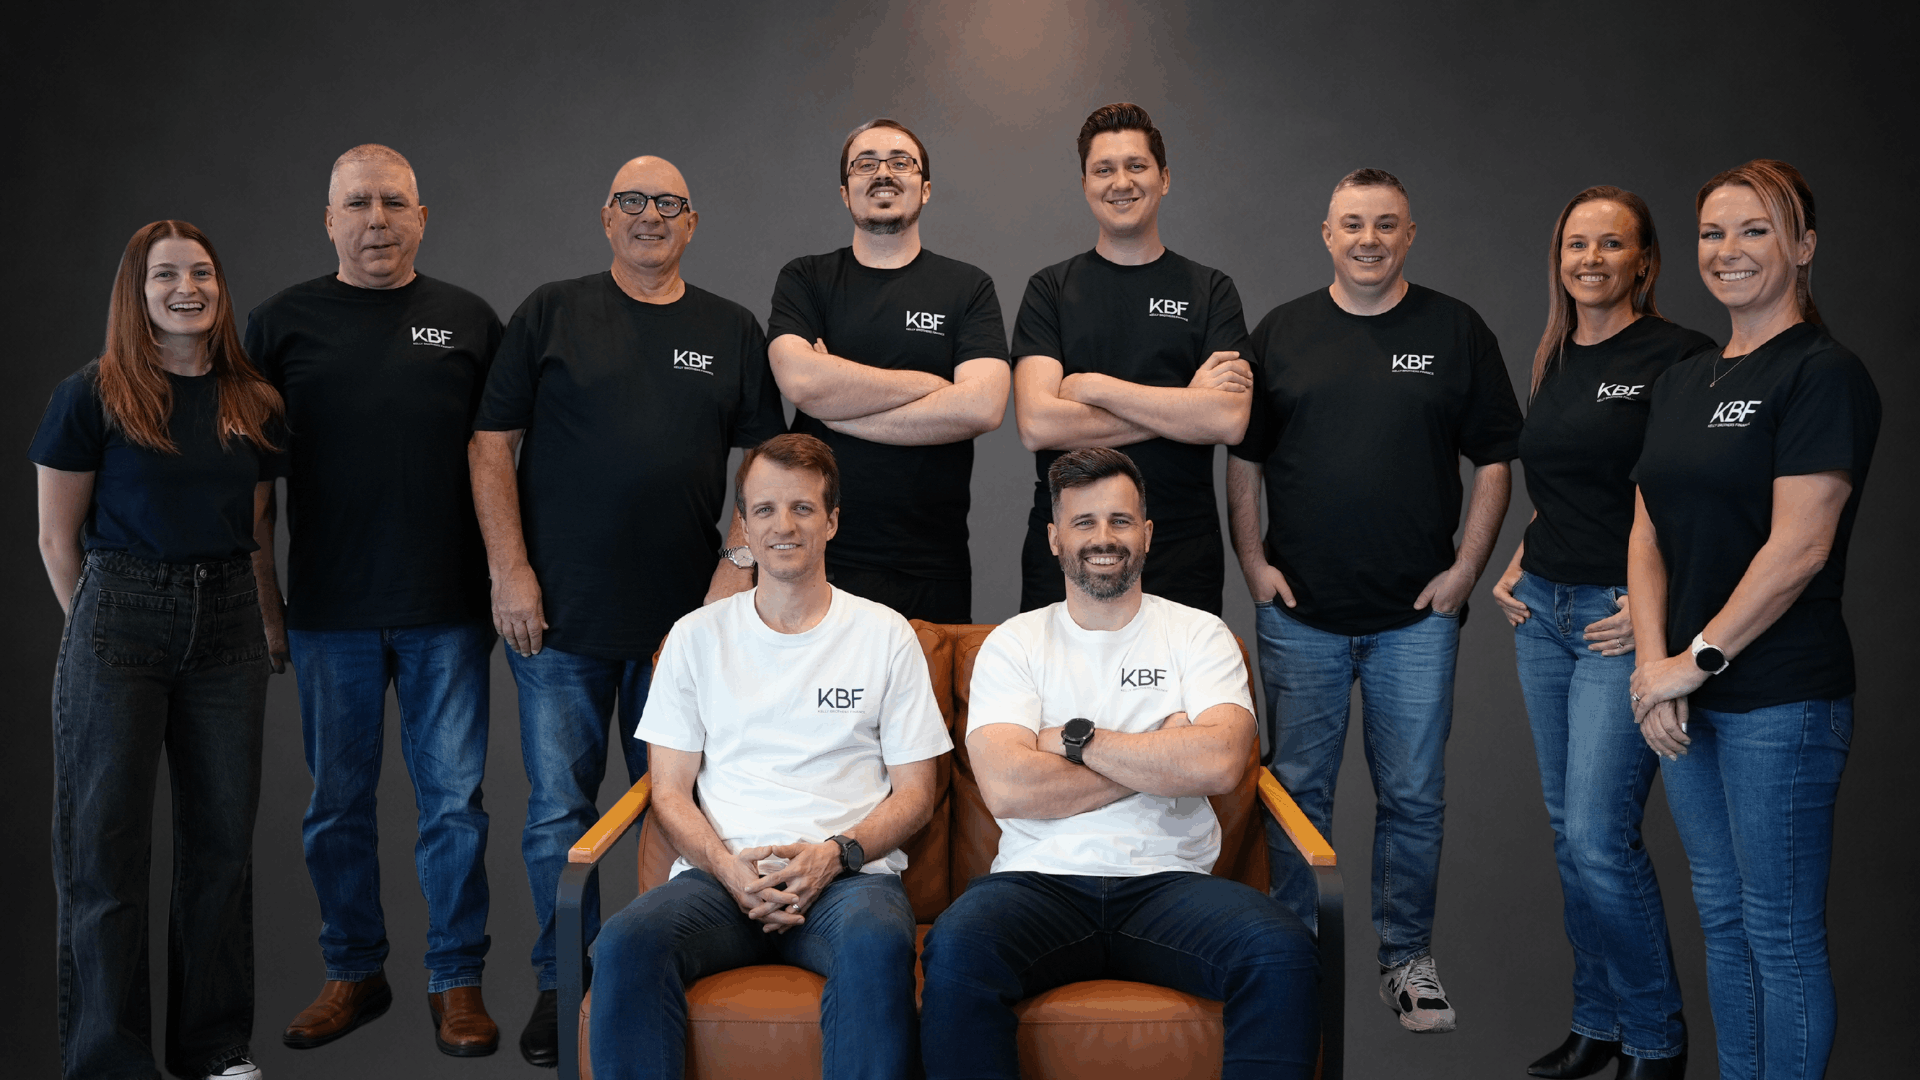
Meet our directors Tom & Steve Kelly, the local First Home Loan experts who work with North Brisbane buyers and investors.
What are the First Home Loan steps?
1. Schedule a free chat here
A free 30-minute chat tells you what you can borrow, what deposit you need, and which first home buyer schemes you actually qualify for.
2. We find the right loan options
First home files often get knocked back over credit card limits and savings patterns that could have been fixed a month earlier. We compare 60+ lenders including how each treats genuine savings and guarantor structures.
3. Start your application, no pressure
If you decide to go ahead, we put the file together, deal with the lender and keep you updated, so you get one credit enquiry rather than several.
4. First Home Loan support!
Tom Kelly works with first home buyers across Brisbane Northside, from Chermside to Wavell Heights. Call him on 0437 403 993.
Schedule a call today:
We negotiate with 60+ lenders for you, including the major Australian First Home Loan banks & lenders.
How do first home loans work in North Brisbane?
A first home loan is a standard home loan paired with the schemes you qualify for. The federal First Home Guarantee lets eligible buyers purchase with a 5% deposit and no Lenders Mortgage Insurance.
Queensland adds a first-home transfer duty concession — nil on new homes and on established homes to $700,000 — plus a $30,000 grant on new builds. Start with pre-approval to fix your budget.
How much deposit do I need as a first home buyer?
Under the First Home Guarantee, as little as 5% with no LMI. Outside the scheme, most lenders want 10% with LMI, or 20% to avoid it entirely.
Genuine savings history matters as much as the amount — lenders like to see the deposit built over three months. We check which scheme fits before you commit, for first buyers from Stafford to Mitchelton.
Can I combine the First Home Owner Grant with stamp duty concessions?
Yes. The $30,000 Queensland First Home Owner Grant applies to new builds under $750,000, and it can generally be combined with the first-home transfer duty concession on eligible purchases.
On a new home the duty concession can bring transfer duty to nil with no price cap, which stacks meaningfully with the grant. Eligibility turns on your contract date and property, so we confirm both before you sign in Kedron or Gordon Park.
Why use a broker for a first home loan instead of a bank?
Start with pre-approval, not listings. Knowing your real ceiling stops you inspecting outside budget and makes your offer credible to agents in a fast inner-north market.
A bank shows you one rate card; we compare 60+ lenders and every scheme you qualify for. Tom Kelly works with first home buyers across Brisbane Northside — call him on 0437 403 993.
