Self Employed Home Loan North Brisbane
Self employed and ready to buy or refinance?
Sole traders, contractors and company directors are assessed differently by every lender. We know which ones read your income properly.
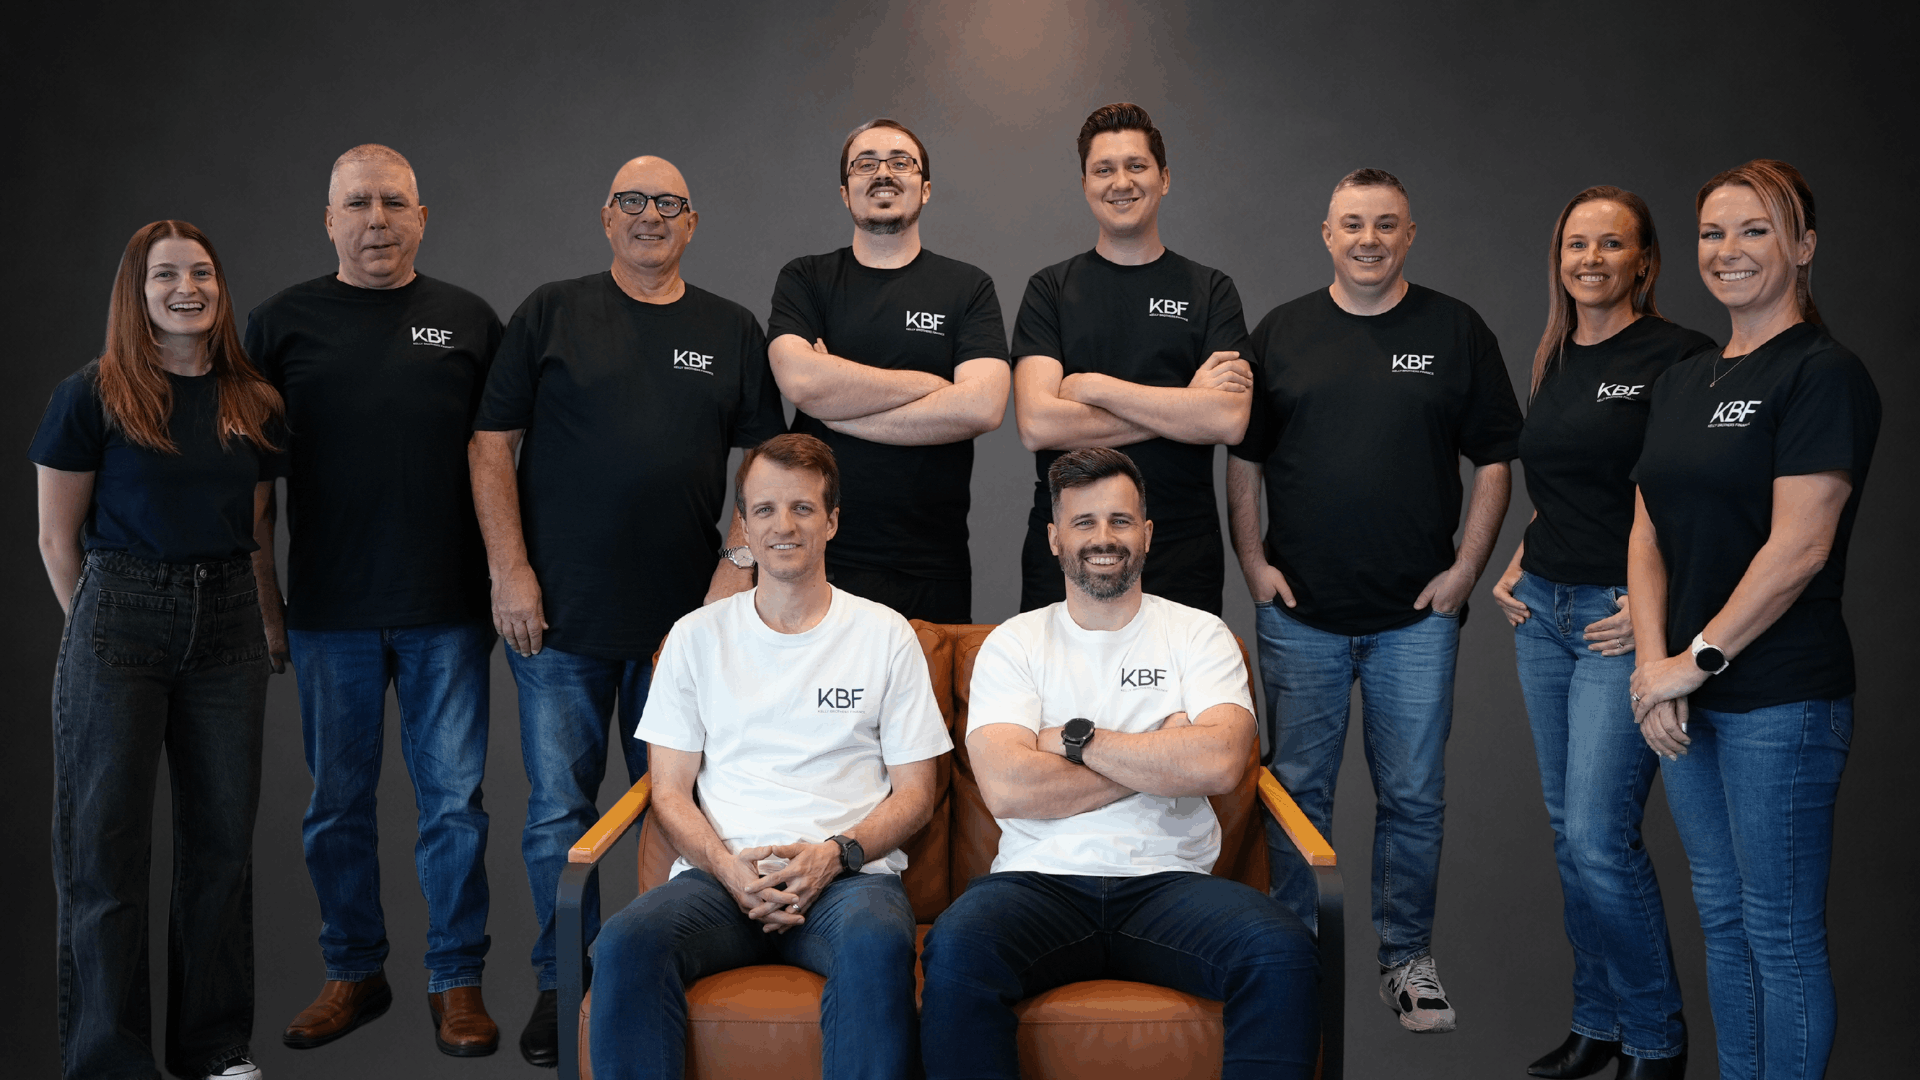
Meet our directors Tom & Steve Kelly, the local Self Employed Home Loan experts who work with North Brisbane buyers and investors.
What are the Self Employed Home Loan steps?
1. Schedule a free chat here
Bring your last two years of tax returns or your recent BAS, and a free chat tells you what you can realistically borrow across our lender panel.
2. We find the right loan options
One lender counts add-backs in full, another discounts them, and a third wants two years of consistent trading first. We compare 60+ to find the one that fits your business.
3. Start your application, no pressure
If your recent figures understate current trading, alt-doc lending using BAS or bank statements can work instead. We'll package whichever approach suits your file best, then handle it to settlement.
4. Self Employed Home Loan support!
Kelly Brothers Finance helps self-employed clients across North Brisbane's trades, professional services and small business community. Call (07) 3847 9450.
Schedule a call today:
We negotiate with 60+ lenders for you, including the major Australian Self Employed Home Loan banks & lenders.
Can self-employed borrowers get a standard home loan?
Yes. Sole traders, contractors and company directors are assessed differently by every lender, so the key is finding one whose policy reads your income properly.
With the right lender you access the same rates as everyone else, not a penalty product. Company directors should also see business owner options.
What documents do I need?
For full-doc, two years of tax returns and notices of assessment. For alt-doc, your recent BAS or bank statements can stand in, which suits newer businesses or a strong recent year.
Bring whichever you have and we'll give you a realistic borrowing figure. We compare 60+ lenders including specialist self-employed funders for clients across Stafford and Mitchelton.
How do lenders treat add-backs differently?
One lender counts add-backs like depreciation and interest in full, another discounts them, and a third wants two years of consistent trading first. We compare 60+ to find the one that fits your business.
That single difference can move borrowing power by a large margin, which is why the lender choice matters more than the headline rate. Salaried professionals with variable income see professional home loans.
What if my current trading is stronger than my last return?
Alt-doc lending using BAS or bank statements can work instead of relying solely on tax returns, assessing the business on where it is now rather than a dated return.
An accountant's declaration often supports it. Call (07) 3847 9450 to talk through your file across our 60+ lender panel.
